Sweden's Heritage Board Hands a SEK 4 Million Accounting and BI Deal to a Single Bidder
Standfirst
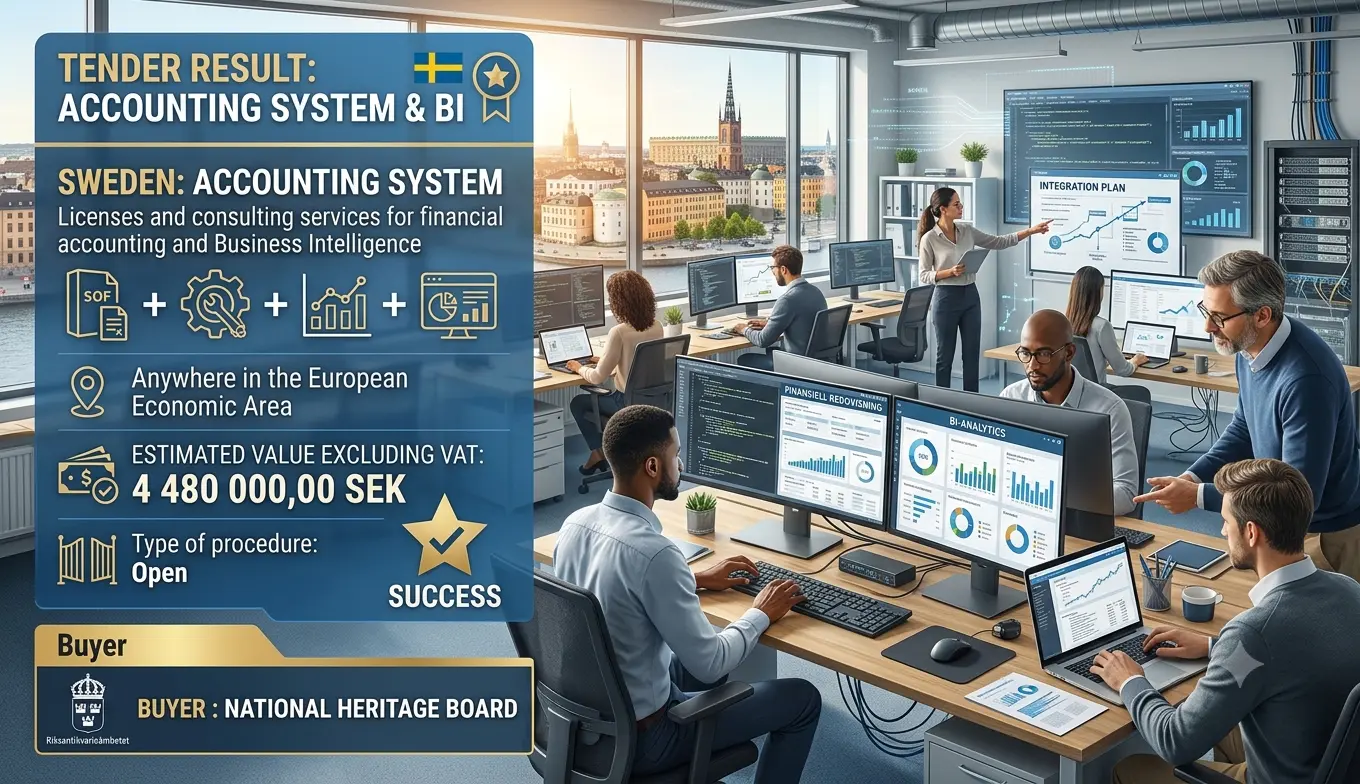
Riksantikvarieämbetet, Sweden's National Heritage Board, has awarded a contract for accounting system licences and consulting services, including Business Intelligence tools, to Transformant Group AB. The contract covers a two-year term from December 2026, with an option to extend by a further 24 months. Only one tender was received, and the awarded value of SEK 3,942,200 came in below both the estimated value of SEK 4,480,000 and the winning tender value of SEK 4,095,300.
Introduction
Public agencies run on financial data. Payroll, invoices, budget follow-up, annual reporting and management analysis all depend on accounting systems that work reliably and produce information that decision-makers can trust. For a cultural heritage authority like Riksantikvarieämbetet, which manages Sweden's museums, archaeological sites, historic buildings and heritage registers, those systems are not the main business, but they are essential to running it.
The agency has now concluded a procurement for accounting system licences and associated consulting services, together with Business Intelligence tools. Business Intelligence, or BI, refers to software that turns raw financial and operational data into reports, dashboards and analysis. It allows managers to see how budgets are being used, where costs are rising and how activities are performing.
The contract was awarded to Transformant Group AB, a medium-sized Swedish company based in Stockholm. The procurement attracted only one tender, and the notice is unusual in its structure: it lists nine "lots," but most of them are not commercial packages. They are administrative sections of the procurement documents, such as exclusion grounds, qualification requirements and evaluation criteria, that have been given lot identifiers in the notice. Only four of the nine identifiers correspond to actual commercial lots.
This article explains what was bought, who was involved, how the procurement was structured, and what the single-bid outcome signals for suppliers in the Swedish public sector software market.
Why This Contract Matters
This contract matters because it shows how a smaller Swedish central government agency buys the financial software it depends on. The estimated value of SEK 4.48 million over two years, with a possible extension to four years, is modest by the standards of large IT procurements. But for an agency with a cultural heritage mandate rather than a technology mandate, getting the right accounting and BI tools matters.
It also matters because only one tender was received. In an open procedure, any qualifying supplier could have bid. The fact that only one did raises questions about the breadth of competition in this segment of the Swedish public sector software market. It may be that the agency's existing systems are so entrenched that only the incumbent or its partner could realistically bid. It may be that the combination of accounting licences, BI tools and consulting services is too specific for most suppliers. The notice does not explain, and the contracting authority has not disclosed this information.
The contract also matters because of its multi-lot structure. The notice records nine lot identifiers, which could mislead a casual reader into thinking nine separate contracts were awarded. In fact, the procurement appears to have been a single commercial engagement covering accounting licences, accounting consulting, BI licences and BI consulting, with the other lot identifiers serving as administrative sections of the procurement documents.
Contract Timeline
- Previous notice: ceba2801-ec5d-407b-9041-7943c809ab0e-01
- Winner selected: 8 September 2026
- Contract concluded: 1 October 2026
- Notice dispatched: 1 October 2026
- Notice published: 2 October 2026
- Contract start date: 1 December 2026
- Contract end date: 30 November 2028
- Maximum renewals: 1
- Renewal duration: 24 months
Contract Overview
The contract covers user licences with associated consulting services for financial accounting and Business Intelligence. It is classified as a supplies contract under CPV 48444000 (accounting system), with an additional classification of CPV 48440000 (financial analysis and accounting software package).
The procurement was conducted as an open procedure under Directive 2014/24/EU. It is not a framework agreement and does not use a dynamic purchasing system. It is not financed with EU funds and is not covered by the Government Procurement Agreement. The place of performance is anywhere in the European Economic Area, according to the notice.
The estimated value excluding VAT was SEK 4,480,000. The value of all contracts awarded in the notice was SEK 3,942,200. The winning tender was valued at SEK 4,095,300. These three figures do not align, and the notice does not explain the differences. The contracting authority has not disclosed this information.
The contract runs from 1 December 2026 to 30 November 2028, with a maximum of one renewal of 24 months. That means the total potential duration is four years, running to 30 November 2030 if the renewal is exercised.
Key Contract Details
| Notice ID | 678461-2026 |
| OJ S issue | 191/2026 |
| Publication date | 2 October 2026 |
| Contracting authority | Riksantikvarieämbetet (Swedish National Heritage Board) |
| Contract type | Supplies |
| Main CPV code | 48444000 – Accounting system |
| Additional CPV code | 48440000 – Financial analysis and accounting software package |
| Procedure type | Open procedure |
| Legal basis | Directive 2014/24/EU |
| Winner | Transformant Group AB |
| Winning tender value | SEK 4,095,300 |
| Value of all contracts awarded | SEK 3,942,200 |
| Estimated value excluding VAT | SEK 4,480,000 |
| Number of tenders | 1 |
| Award criteria | Price – 100% for all lots |
| Contract duration | 1 December 2026 to 30 November 2028 |
| Maximum renewals | 1 renewal of 24 months |
| Framework agreement | No |
| Dynamic purchasing system | No |
| EU funding | No |
| GPA covered | No |
| Subcontracting | Yes, declared by the winner; value and percentage not known |
| Review body | Förvaltningsrätten (Administrative Court) |
Project Scope
The scope is user licences with associated consulting services for financial accounting and Business Intelligence. The notice describes it in Swedish as "användarlicencer med tillhörande konsulttjänster för ekonomiredovisning och Business Intelligence" — user licences with associated consulting services for financial accounting and BI.
That means the contract has four practical components: licences for accounting software, consulting services for accounting software, licences for BI software, and consulting services for BI software. These correspond to the four commercial lots identified in the notice as LOT-0005 (Ekonomiredovisning – licenser), LOT-0006 (Ekonomiredovisning – konsulttjänster), LOT-0007 (Business Intelligence – licenser) and LOT-0008 (Business Intelligence – konsulttjänster).
The notice does not disclose which specific accounting or BI products are involved, how many user licences are required, what consulting hours are expected, or how the work will be divided between licences and services. The contracting authority has not disclosed this information.
The other five lot identifiers in the notice — LOT-0001 (Uteslutningsgrunderna, or exclusion grounds), LOT-0002 (Kvalificering av anbudsgivare samt obligatoriska krav, or qualification of tenderers and mandatory requirements), LOT-0003 (Obligatoriska krav på anbudsgivaren, or mandatory requirements on the tenderer), LOT-0004 (Informationsfrågor, or information questions) and LOT-0009 (Utvärderingskriterier användarvänlighet, or evaluation criteria usability) — are not commercial packages. They are administrative and qualification sections of the procurement documents that have been assigned lot identifiers in the notice. The winner is recorded against all nine identifiers with the same tender value, which suggests the tender covered the whole scope and the notice has allocated it across all sections.
About the Contracting Authority
The buyer is Riksantikvarieämbetet, the Swedish National Heritage Board. It is classified as a central government authority with recreation, culture and religion as its main activity. Its registration number is 2021001090.
The agency's registered address is Box 1114, Visby, postcode 62122, on the island of Gotland. Its contact point for this procurement is Birgitta Lidman, whose email address is birgitta.lidman@raa.se. Its website is raa.se.
Riksantikvarieämbetet is the central administrative agency for cultural heritage in Sweden. It is responsible for heritage policy, archaeological excavations, historic buildings and monuments, and the management of Sweden's cultural heritage information. It operates museums and heritage sites and provides expert advice to government and other public bodies.
The agency is both the buyer and the organisation signing the contract. It defined the requirements for accounting and BI licences and services, ran the open procedure, received one tender and concluded the contract with Transformant Group AB.
About the Organisations Involved
Riksantikvarieämbetet
Riksantikvarieämbetet is the contracting authority. It is a central government agency responsible for cultural heritage in Sweden. Its role in this procurement is as buyer and signatory of the contract.
It is registered in Visby, with registration number 2021001090. Although its registered office is on Gotland, the procurement's place of performance is recorded as anywhere in the European Economic Area, which suggests the agency's financial systems may be operated or supported remotely, or that the contract does not require on-site delivery at a specific location.
The agency's need for accounting and BI tools is administrative rather than mission-critical to its heritage work, but it is essential to running the organisation. The procurement reflects the agency's decision to buy licences and consulting services rather than develop or maintain bespoke systems.
Transformant Group AB
Transformant Group AB is the winning bidder. It is classified as a medium-sized economic operator. Its registration number is 5590914692, and its registered office is at Skeppsbron 46, Stockholm, postcode 111 30, in the Stockholms län region.
Its contact point for this procurement is Calle Andersson, whose email address is sales@transformant.se. The notice does not disclose the company's specific capabilities, its product portfolio, or its relationship with any accounting or BI software vendor. The contracting authority has not disclosed this information.
Transformant Group AB submitted the only tender for the procurement, identified as "Riksantikvarieämb Ekonomi BI," with a value of SEK 4,095,300. It declared subcontracting, but the value and percentage of subcontracting are not known.
The company is recorded as the winner of all nine lot identifiers in the notice. As explained above, four of those are commercial lots and five are administrative sections. The tender appears to have covered the whole scope, and the notice has allocated it across all identifiers.
Förvaltningsrätten
Förvaltningsrätten, the Swedish Administrative Court, is listed as the review organisation and the organisation providing more information on review procedures. Its registration number is 202100-2742, and it is based in Stockholm, postcode 115 76.
Its role is to hear appeals from bidders who believe a procurement has been conducted improperly. The notice refers bidders to the procurement documents for review deadlines rather than specifying them in the notice itself. The specific administrative court with jurisdiction is not named in the notice beyond "Förvaltningsrätten," though Stockholm is listed as its location.
Other organisations
The notice does not identify any other tenderers, consortium members, framework participants or subcontractors. Only one tender was received. No other organisation materially affects the understanding of this award.
Procurement Analysis
The procurement was conducted as an open procedure under Directive 2014/24/EU. The open procedure is the standard route for a contract of this size and allows any qualifying supplier to bid.
The award criterion was price alone, weighted at 100% for every lot identifier in the notice. This is the simplest possible evaluation method. There were no quality criteria, no technical scoring and no sustainability weighting. The lowest-priced compliant bid would win.
Only one tender was received. In an open procedure, that is a notable outcome. It means the agency had no competitive benchmark for the price, and no opportunity to compare technical approaches. The absence of competition also means there is no evidence about whether the price represents market value.
The winning tender value was SEK 4,095,300. The value of all contracts awarded in the notice was SEK 3,942,200. The estimated value was SEK 4,480,000. These figures do not reconcile. The awarded value is lower than the winning tender value, which is unusual. It may be that the awarded value represents a different scope, that some options were not exercised, or that the figures have been recorded inconsistently in the notice. The contracting authority has not explained this discrepancy.
The contract is not covered by the Government Procurement Agreement. The notice does not explain why. The contract is not financed with EU funds.
The contract runs for two years, with one possible renewal of 24 months. That is a relatively short initial term for an accounting system, where implementation and migration costs are often significant. A two-year term gives the agency flexibility, but it also means the supplier has a limited window to recoup any upfront investment. The renewal option provides some continuity if the arrangement works well.
The notice records that the winner declared subcontracting, but neither the value nor the percentage is known. That means part of the work will be delivered by another company or companies, but the notice does not say who they are or what they will do. The contracting authority has not disclosed this information.
The place of performance is recorded as anywhere in the European Economic Area. That is unusual for an accounting system contract, which would normally be performed at the buyer's premises or remotely from the supplier's offices. It may indicate that the agency has staff or systems in multiple locations, or that the notice uses a standard EEA-wide placeholder.
Additional Procurement Facts
- Legal basis: Directive 2014/24/EU.
- Procedure: Open procedure, not accelerated.
- Award criteria: Price – 100% for all lot identifiers.
- Number of tenders: 1.
- Winner: Transformant Group AB, a medium-sized Swedish company.
- Winning tender value: SEK 4,095,300.
- Value of all contracts awarded: SEK 3,942,200.
- Estimated value: SEK 4,480,000 excluding VAT.
- Contract duration: 1 December 2026 to 30 November 2028.
- Renewal: Maximum 1 renewal of 24 months.
- EU funding: The procurement project is not financed with EU funds.
- GPA: Not covered by the Government Procurement Agreement.
- Framework agreement: None.
- Dynamic purchasing system: None.
- Strategic procurement: None.
- Subcontracting: Declared by the winner; value and percentage not known.
- Review body: Förvaltningsrätten (Administrative Court).
- Value discrepancy: The awarded value is lower than the winning tender value, and both differ from the estimated value. The notice does not explain this.
Market & Industry Perspective
The Swedish public sector accounting software market is mature and concentrated. A small number of vendors, including international providers and Swedish specialists, dominate the market for financial systems in government agencies. These systems are typically licensed, implemented and supported through authorised partners, and switching costs are high because of data migration, integration and user training.
This contract reflects that market structure. It combines licences and consulting services for both accounting and BI, which suggests the agency is buying an integrated solution rather than separate components. The fact that only one tender was received is consistent with a market where the incumbent supplier or its partner has a strong advantage.
The Business Intelligence element is significant. BI tools are increasingly important in public sector financial management, because they allow agencies to analyse spending, forecast budgets and report to government in more sophisticated ways. Combining BI with core accounting licences in a single procurement is a practical way to ensure the two systems work together.
The two-year term with a 24-month renewal option is relatively short. In accounting software, implementation and migration can take months, and the agency will want to see a return on that investment. A short initial term gives the agency leverage to renegotiate or re-procure if performance is unsatisfactory, but it may also deter suppliers that prefer longer commitments.
The price-only award criterion is notable. It means the agency did not formally evaluate technical quality, implementation approach or support capability at the award stage. Those factors may have been assessed as mandatory requirements, but they did not influence the scoring. In a single-bid situation, the price criterion becomes largely a formality, since there is no competing price to compare against.
Economic Significance
At SEK 4.48 million estimated value over two years, with a possible extension to four years, this is a modest contract. It is small relative to the agency's overall budget and small relative to the Swedish public sector IT market. Its economic significance lies mainly in what it enables: reliable financial management and analysis for a central government agency.
The contract also has a modest direct economic effect. The money flows to Transformant Group AB, a medium-sized Swedish company, and to any subcontractors it engages. That supports employment and economic activity in Sweden's IT services sector.
The single-bid outcome has an economic dimension. Without competition, the agency has less assurance that it is paying a competitive price. The fact that the awarded value came in below both the estimate and the winning tender value may indicate that the agency negotiated a reduction, or that the notice records the figures inconsistently. Either way, the absence of competing bids means there is no market test of the price.
The BI component has economic value that goes beyond the contract price. Better financial analysis can help the agency allocate resources more effectively, identify inefficiencies and report more transparently. For a public body accountable to government and citizens, that has real value.
Future Procurement Opportunities
The most immediate future opportunity is the renewal option. The contract runs from 1 December 2026 to 30 November 2028, with a maximum of one renewal of 24 months. If the agency exercises the renewal, the contract would run to 30 November 2030. Suppliers should watch for a renewal decision as the initial term approaches its end.
If the agency decides not to renew, a new procurement would be required. That would create an opportunity for other suppliers to compete, assuming the agency structures the procurement to attract multiple bids. Suppliers should monitor the agency's procurement notices for any follow-on competition.
There may also be opportunities arising from additional licences, consulting hours or BI modules during the contract term. The notice does not disclose whether the contract includes options for such additions, but accounting and BI contracts often do.
More broadly, other Swedish central government agencies have similar needs for accounting and BI systems. Suppliers with a proven track record in this segment should monitor procurement activity across the Swedish public sector, including through the national procurement portal and TED.
Opportunities for Suppliers
- Accounting software partners: Suppliers with authorised partner status for major accounting software vendors are the most likely candidates for similar contracts.
- BI specialists: The contract combines accounting and BI. Suppliers with capability in both areas are better positioned than those with only one.
- Consulting providers: The contract includes consulting services for both accounting and BI. Suppliers with implementation and support expertise may find opportunities.
- Subcontractors: The winner declared subcontracting. Suppliers in the accounting or BI ecosystem may find opportunities through Transformant Group AB's supply chain.
- Monitoring the buyer: Suppliers should monitor Riksantikvarieämbetet's procurement notices for future opportunities, including the renewal decision.
- Other Swedish agencies: The market for accounting and BI systems across Swedish central government is broader than this single contract. Suppliers should monitor the national procurement portal.
What Businesses Should Watch
- Whether the renewal is exercised: The contract has one renewal option of 24 months. Suppliers should watch for the agency's decision as the initial term ends.
- Whether a follow-on procurement is launched: If the agency decides not to renew or wants a different solution, a new competition would follow.
- Whether the value discrepancy is explained: The notice records three different values for the contract. Suppliers should watch for clarification.
- Whether subcontractors are disclosed: The winner declared subcontracting but did not name the subcontractors. Suppliers should watch for further disclosure.
- Whether other agencies follow suit: If this procurement model works well, other Swedish agencies may adopt a similar approach.
- Whether competition improves: The single-bid outcome is a concern. If future procurements attract more bidders, that would indicate a healthier market.
SwedenTenders.com Procurement Intelligence
This contract represents a broader procurement trend in Sweden and across Europe: public agencies are bundling core financial systems with Business Intelligence tools into single procurements. That approach recognises that accounting data is only useful if it can be analysed, and that buying the two capabilities together reduces integration risk. It favours suppliers that can offer both accounting and BI capability, either directly or through partnerships, and it disadvantages suppliers that only cover one side of the equation.
The award is strategically important because it shows how a smaller central government agency approaches the procurement of business-critical software. The agency chose an open procedure, used price as the only award criterion, and accepted a single bid. That combination gives the agency limited leverage on price and no formal comparison of technical quality. The two-year term with a renewal option provides some flexibility, but the agency will depend on the supplier for the duration of the contract.
Suppliers can learn several things from this procurement. First, bundling matters. The contract combines accounting licences, accounting consulting, BI licences and BI consulting. Suppliers that can cover the full scope have an advantage over those that can only cover part of it. Second, single-bid outcomes are possible even in open procedures. Suppliers that assume competition will always be strong may miss opportunities. Third, price-only evaluation simplifies bidding but does not eliminate the need for technical compliance. Fourth, subcontracting is permitted and was declared, which means the winning supplier may not deliver everything itself. Fifth, the notice structure can be confusing. The nine lot identifiers do not represent nine commercial packages, and suppliers reading the notice should distinguish between commercial lots and administrative sections.
Suppliers should position themselves accordingly. They should build capability across accounting and BI, either directly or through partnerships. They should monitor the agency's renewal decision and prepare for a possible follow-on procurement. They should examine the value discrepancies in the notice and seek clarification if they intend to bid in future. And they should look beyond this single contract to the broader market of Swedish central government agencies with similar needs.
Future contracts in this market are likely to evolve in two directions. First, more agencies will bundle accounting and BI into single procurements, following the logic that financial data should be analysable as well as recordable. Second, agencies may move away from price-only evaluation towards models that reward implementation quality, support capability and integration experience. Suppliers that can demonstrate those qualities, alongside competitive pricing, will be best positioned. Suppliers that compete on price alone will find themselves in a market where the real value lies in delivering a working system, not just the lowest bid.
Supplier Takeaways
- The contract bundles accounting licences, accounting consulting, BI licences and BI consulting. Suppliers that can cover the full scope have an advantage.
- Only one tender was received, despite an open procedure. Competition in this segment may be weaker than expected.
- Price was the only award criterion, weighted at 100%. There was no formal quality evaluation.
- The winning tender value (SEK 4,095,300), the awarded value (SEK 3,942,200) and the estimated value (SEK 4,480,000) do not reconcile. Suppliers should seek clarification.
- The winner declared subcontracting, but the value, percentage and identity of subcontractors are not known.
- The contract runs from 1 December 2026 to 30 November 2028, with one possible renewal of 24 months.
- The notice records nine lot identifiers, but only four are commercial lots. The other five are administrative sections.
- The contract is not covered by the GPA and is not financed with EU funds.
- The review body is Förvaltningsrätten, the Swedish Administrative Court.
- The winner, Transformant Group AB, is a medium-sized Swedish company based in Stockholm.
Key Takeaways
- Riksantikvarieämbetet, Sweden's National Heritage Board, awarded a contract for accounting system licences, BI licences and associated consulting services to Transformant Group AB.
- The estimated contract value was SEK 4,480,000 excluding VAT.
- The value of all contracts awarded in the notice was SEK 3,942,200, while the winning tender value was SEK 4,095,300. The notice does not explain the difference.
- Only one tender was received. The contract was awarded on price alone, weighted at 100%.
- The contract runs from 1 December 2026 to 30 November 2028, with a maximum of one renewal of 24 months.
- The procurement was an open procedure under Directive 2014/24/EU.
- It is not a framework agreement, not a dynamic purchasing system, not EU-funded and not GPA-covered.
- The winner declared subcontracting, but details are not known.
- The notice lists nine lot identifiers, of which four are commercial lots and five are administrative sections of the procurement documents.
- The review body is Förvaltningsrätten, the Swedish Administrative Court.
Conclusion
Riksantikvarieämbetet has awarded a contract for accounting system licences, Business Intelligence licences and associated consulting services to Transformant Group AB. The contract, worth just under SEK 4 million over two years with a possible extension to four, will support the agency's financial management and analysis.
The procurement was conducted as an open procedure, but only one tender was received. That single-bid outcome is the most notable feature of the award. It suggests either that the agency's requirements were closely aligned with one supplier's offering, or that the market for combined accounting and BI licences and services in the Swedish central government segment is narrow. The price-only award criterion means the agency had no formal way to compare technical quality, and the absence of competing bids means it had no market test of price.
For suppliers, the contract reinforces the importance of bundling accounting and BI capability, of monitoring renewal and follow-on opportunities, and of understanding the difference between commercial lots and administrative sections in TED notices. For the agency, the challenge will be to ensure that the system delivers the financial visibility it needs, and that future procurements attract enough competition to provide genuine value. The notice leaves several questions unanswered the value discrepancies, the identity of subcontractors, the specific products involved but the core award is clear: Transformant Group AB will supply and support the agency's accounting and BI environment for at least the next two years.
Source: Tenders Electronic Daily (TED), Contract Award Notice 678461-2026, Official Journal of the European Union, OJ S 191/2026, published on 2 October 2026.
Fresh and verified Tenders from Sweden. Find, search and filter Tenders/Call for bids/RFIs/RFPs/RFQs/Auctions published by the government, public sector undertakings (PSUs) and private entities.
- 1,000+ Tenders
- Verified Tenders Only
- New Tenders Every Day
- Tenders Result Data
- Archive & Historical Tenders Access
- Consultants for RFI/RFP/RFQ
- Tender Notifications & Alerts
- Search, Sort, and Filter Tenders
- Bidding Assistance & Consulting
- Customer Support
- Publish your Tenders
- Export data to Excel
- API for Tender Data
- Tender Documents
Fill out the form below and you will receive a call from us within 24 hours.
Get FREE SAMPLE TENDERS from Sweden in your email inbox.
Copyright © 2014-2026 SwedenTenders.com. All Rights Reserved.